
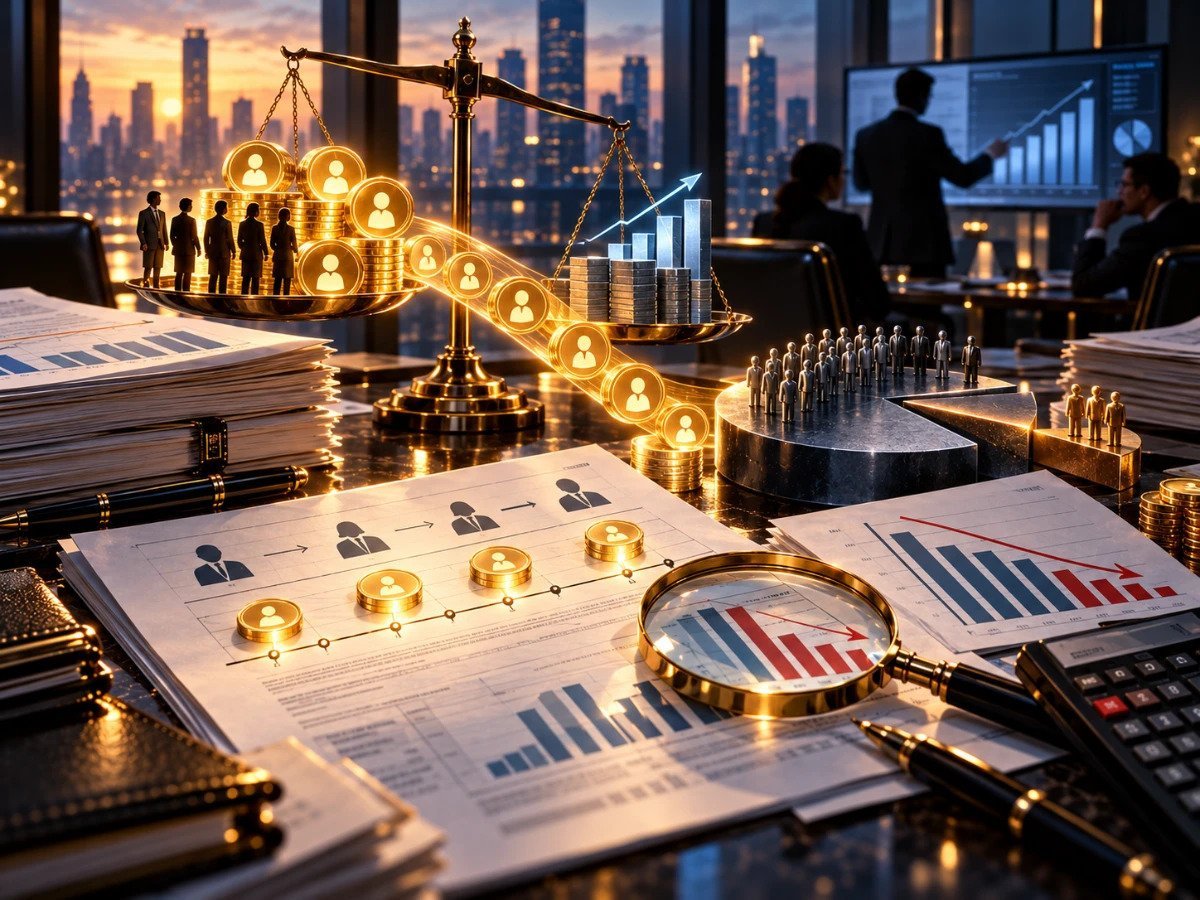
Employee Stock Ownership Plans (ESOPs) are widely celebrated as a win-win compensation tool—aligning employee incentives with company growth while preserving cash flow. However, when complex accounting rules, aggressive promoter discretion, and poor corporate governance intersect, ESOPs can be manipulated to dress up earnings, dilute minority shareholder value, and obscure a company’s true financial health.
The Hidden Risks: 7 Ways ESOPs Can Mislead Financial Statements
1. Earnings Manipulation via Opaque Valuation
-
The Trick: Valuing private company stock options artificially low during grant periods to minimize compensation expense reporting.
-
The Impact: Understating employee costs directly inflates reported net income and operating profits, painting a misleadingly rosy picture of the company’s profitability.
2. Excessive Dilution of Minority Shareholders
-
The Trick: Granting massive blocks of stock options to promoters, top executives, or subsidiaries without adequate checks or shareholder approval.
-
The Impact: When these options are exercised, the total share count balloons. Minority shareholders experience severe EPS (Earnings Per Share) dilution, shrinking their proportional ownership and future dividend claims.
3. Bypassing Regulatory Directives (As Seen in Regulatory Interventions)
-
The Trick: Issuing stock options despite explicit warnings, objections, or prohibitions from sectoral regulators (such as insurance, banking, or market watchdogs).
-
The Impact: Companies force through executive grants in defiance of governance rules, leading to subsequent regulatory crackdowns, forced share cancellations, heavy financial penalties, and reputational damage.
4. Asymmetric Rewards Disconnected from Performance
-
The Trick: Structuring ESOP schemes with loose or non-existent vesting hurdles tied to long-term operational performance.
-
The Impact: Executives receive windfall equity rewards regardless of whether shareholder value or fundamental business metrics improved, transferring wealth from public investors to insiders.
5. Masking Cash Flow Pressures
-
The Trick: Using equity-based compensation aggressively to compensate for lack of cash liquidity or inability to pay competitive market-rate salaries.
-
The Impact: While cash burn appears lower on paper, the deferred equity dilution quietly mortgages the company’s future equity value.
6. Repricing Options After Market Dips
-
The Trick: Lowering the exercise price of underwater options when the company’s stock price drops.
-
The Impact: This nullifies the risk inherent in equity compensation, shielding executives from market realities while locking in dilution for everyday shareholders.
7. Off-Balance-Sheet or Subsidiary Complexity
-
The Trick: Issuing stock options through complex subsidiary structures or related-party trusts that obscure the true cost of compensation from consolidated reporting.
-
The Impact: Analysts and retail investors struggle to trace the actual dilution impact and financial liabilities buried deep within corporate hierarchies.
What Investors Should Look For
To protect portfolio investments against aggressive or misleading ESOP practices, scrutinize:
-
Dilution Run-Rate: Review the annual dilution percentage resulting from new stock option grants.
-
Expense Recognition: Ensure stock-based compensation is appropriately expensed under standard accounting practices rather than treated as a non-item.
-
Related-Party Allotments: Check whether disproportionate option pools are flowing to promoters and top management rather than broad-based employee tiers.
