
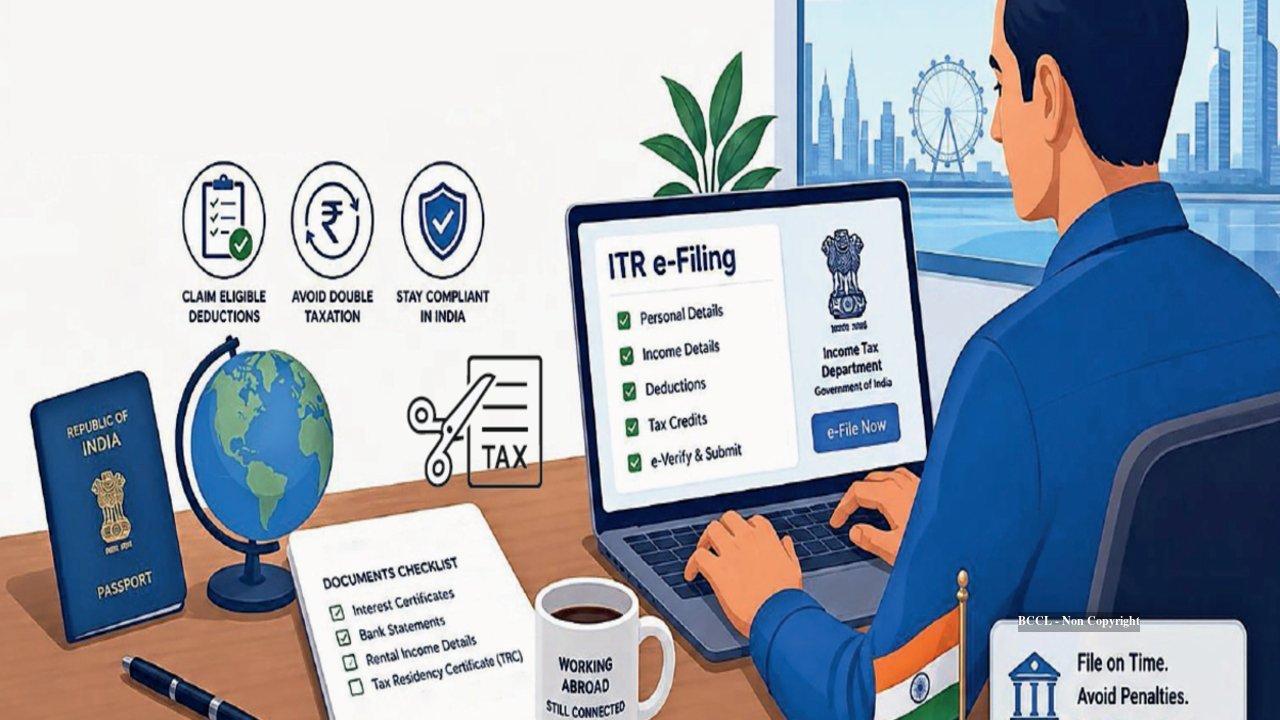
The Income Tax (I-T) Department is ramping up its compliance and enforcement mechanisms, preparing to issue a wave of scrutiny notices to Indian residents who have failed to disclose foreign properties and overseas assets in their tax filings. Leveraging global data-sharing agreements and advanced financial analytics, tax authorities are tightening the net on undisclosed wealth parked abroad.
Key Highlights & Enforcement Drivers
-
Global Information Exchange: Tax authorities are utilizing automatic information-sharing frameworks—such as the Common Reporting Standard (CRS) and the Foreign Account Tax Compliance Act (FATCA)—to cross-verify financial records, property purchases, and bank accounts held overseas by Indian tax residents.
-
Focus on Compliance: The notices target individuals who omitted foreign immovable properties, offshore bank accounts, foreign equity, or other valuable assets in Schedule FA (Foreign Assets) of their Income Tax Returns (ITR).
-
Strict Penalties Under the Black Money Act: Undisclosed foreign assets face severe repercussions under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, which carries steep penalties, heavy taxation rates, and potential prosecution for non-compliance.
Strategic Implications for Taxpayers
-
Zero Tolerance for Omissions: Tax experts advise residents with global exposure to meticulously review their disclosures, as automated data matching leaves little room for oversight.
-
Proactive Correction: With tax authorities increasingly utilizing data analytics to map global holdings, taxpayers are encouraged to ensure transparency and compliance regarding any international assets or inheritances.
