
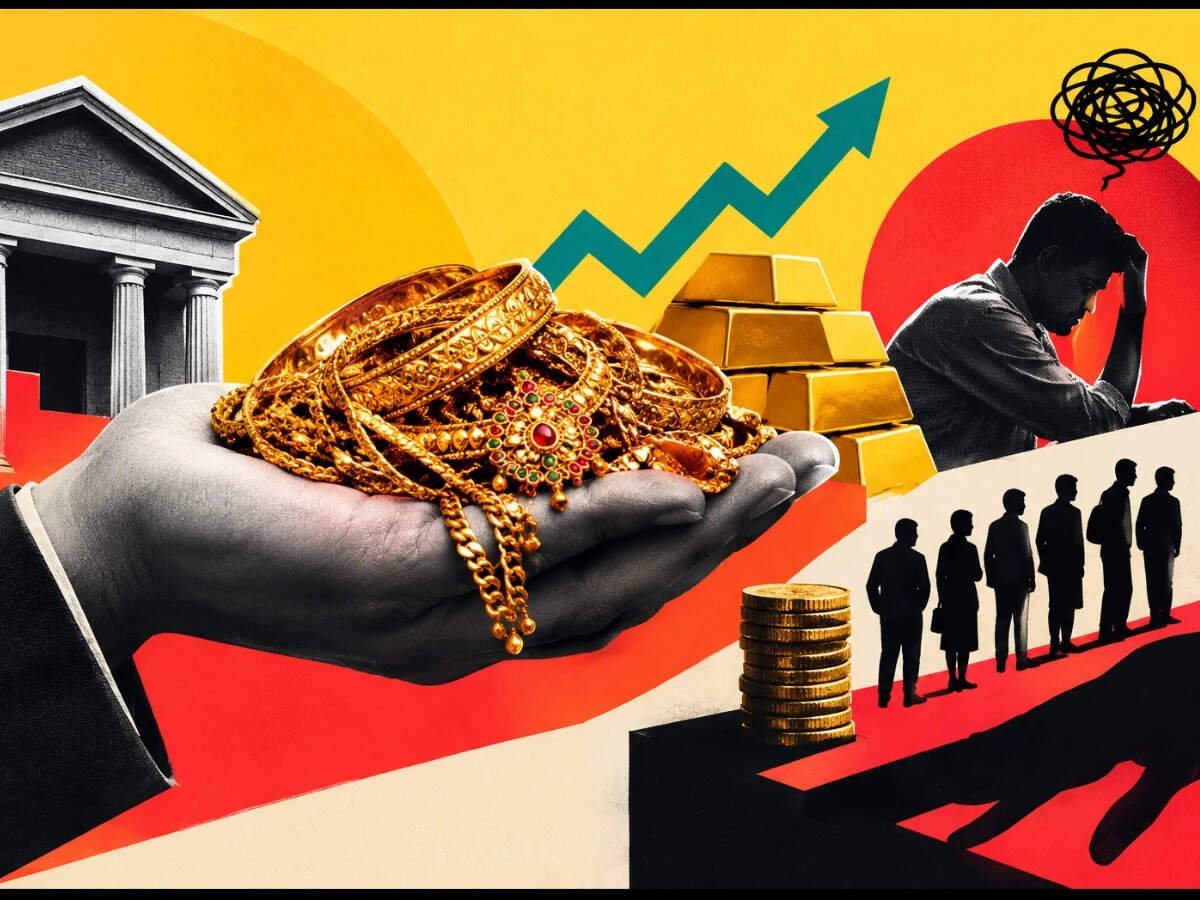
India’s gold loan market—long considered a high-growth, secure bastion for Non-Banking Financial Companies (NBFCs) and traditional lenders—is facing mounting structural headwinds. Driven by soaring household credit demand, gold-backed lending has seen a massive boom. However, a combination of volatile bullion prices, shifting borrower profiles, intensifying competitive pressures, and tightening regulatory oversight threatens to push the sector into a riskier operational environment.
Key Industry Concerns & Risk Drivers
-
Surging Credit Demand vs. Household Stress: As retail inflation and liquidity pressures pinch small businesses and households, reliance on gold loans for immediate working capital and emergency cash has spiked. Analysts warn that underlying borrower stress could lead to higher default and auction rates if borrowers fail to redeem pledged ornaments.
-
Regulatory Pushback and Compliance: The Reserve Bank of India (RBI) has heightened its scrutiny over gold loan NBFCs and banking lenders, cracking down on procedural lapses, cash disbursements above statutory limits, unverified valuation practices, and opaque auction mechanisms.
-
Valuation Volatility: Fluctuations in international gold prices create portfolio risks. Lenders operating close to maximum Loan-to-Value (LTV) ratios face sudden collateral deficits if gold prices correct sharply, squeezing safety margins.
-
Aggressive Market Competition: Traditional commercial banks aggressively cutting rates and expanding into semi-urban and rural pockets have forced specialized NBFCs into margin compression or riskier lending practices to protect their market share.
Sectoral Vulnerability Breakdown
-
Stricter Governance Required: Industry experts emphasize that lenders must tighten appraisal standards, adopt robust digital tracking for collateral storage, and maintain conservative LTV buffers to weather potential economic shocks.
-
Long-Term Outlook: While the secular demand for gold-backed liquidity in India remains robust, lenders will need to pivot from aggressive volume-chasing toward disciplined risk management and transparent borrower communication to ensure sustainable growth.
