

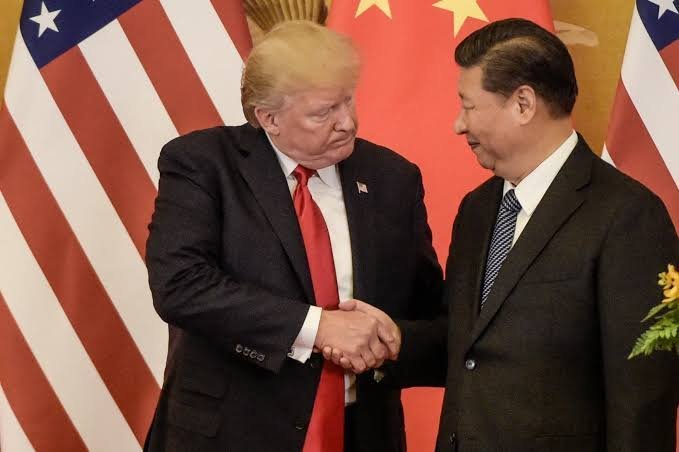
Mainland China and Hong Kong equities pulled back from recent gains as investors adopted a cautious “wait-and-see” approach ahead of the high-profile summit between U.S. President Donald Trump and Chinese President Xi Jinping.
While preliminary diplomatic groundwork—including discussions covering artificial intelligence safety and trade frameworks—kept communication channels open, market participants scaled back aggressive hopes for a major structural breakthrough.
By the midday break, the blue-chip CSI300 index dipped 0.5%, while the Shanghai Composite Index declined 0.4%. In Hong Kong, the benchmark Hang Seng Index fell 0.8%, with the tech-heavy sub-index dropping over 1% as an earlier tech rally lost momentum.
The Trade Summit and Geopolitical Pressures
Market focus centers squarely on the September 24 meeting in Washington, where leaders from the world’s two largest economies are expected to discuss whether to extend a vital trade truce. Economists and think tanks note that while the meeting could introduce a degree of predictability, structural restrictions on high-end technology, security policies, and trade are widely expected to remain.
Compounding regional sentiment, investors also digested rising trade frictions with Europe. The European Central Bank recently highlighted that China’s rapid industrial transformation is putting mounting pressure on European firms, while ratings agency Fitch trimmed its economic growth forecast for China to 4.5%, citing widening macroeconomic imbalances. Consequently, auto stocks and new-energy vehicle manufacturers faced distinct downward pressure, with sector indices slipping up to 1% amid talks of potential foreign tariffs and local-content rules.
Property Shares Rally Amid Targeted Support
Bucking the broader market downturn, Chinese real estate shares surged across both mainland and Hong Kong exchanges
